- From April 2027, pensions will come into the scope of inheritance tax, increasing the need for an effective decumulation strategy.
- Property has come into focus, as one of the largest, though also one of the most complex assets we own.
- As property moves up the agenda, technology needs to evolve to keep up.
Financial planning is entering a new phase.
From April 2027, pensions will come into the scope of inheritance tax, meaning significantly more clients are likely to require tax planning. Combined with changing expectations around later-life lending and estate planning, advisers are increasingly being asked to connect conversations that have traditionally been treated separately.
That shift matters because property is often a client’s largest asset. UK over-55s hold £3.8 trillion in housing wealth, and 93% of advisers believe property should form part of holistic financial planning. The challenge isn’t convincing advisers that property matters. It’s making it easier to bring property into the conversations they’re already having. (source: GOV.UK, FCA)
The FCA’s recent market study into later-life lending reflects this shift, highlighting the need for better information, joined-up advice and more effective consumer support. As financial planning evolves, advisers need better ways to connect property with the rest of a client’s financial picture.
Financial planning is becoming broader
Clients don’t think about their finances in silos.
Retirement planning influences inheritance tax. Property affects later life lending. Family circumstances shape estate planning. Increasingly, these conversations overlap, and clients expect advisers to help them understand how the pieces fit together.
Upcoming inheritance tax changes are accelerating that trend. As more clients require inheritance tax planning, advisers will increasingly need to consider how pensions, investments and property interact.
The challenge isn’t awareness. It’s integration
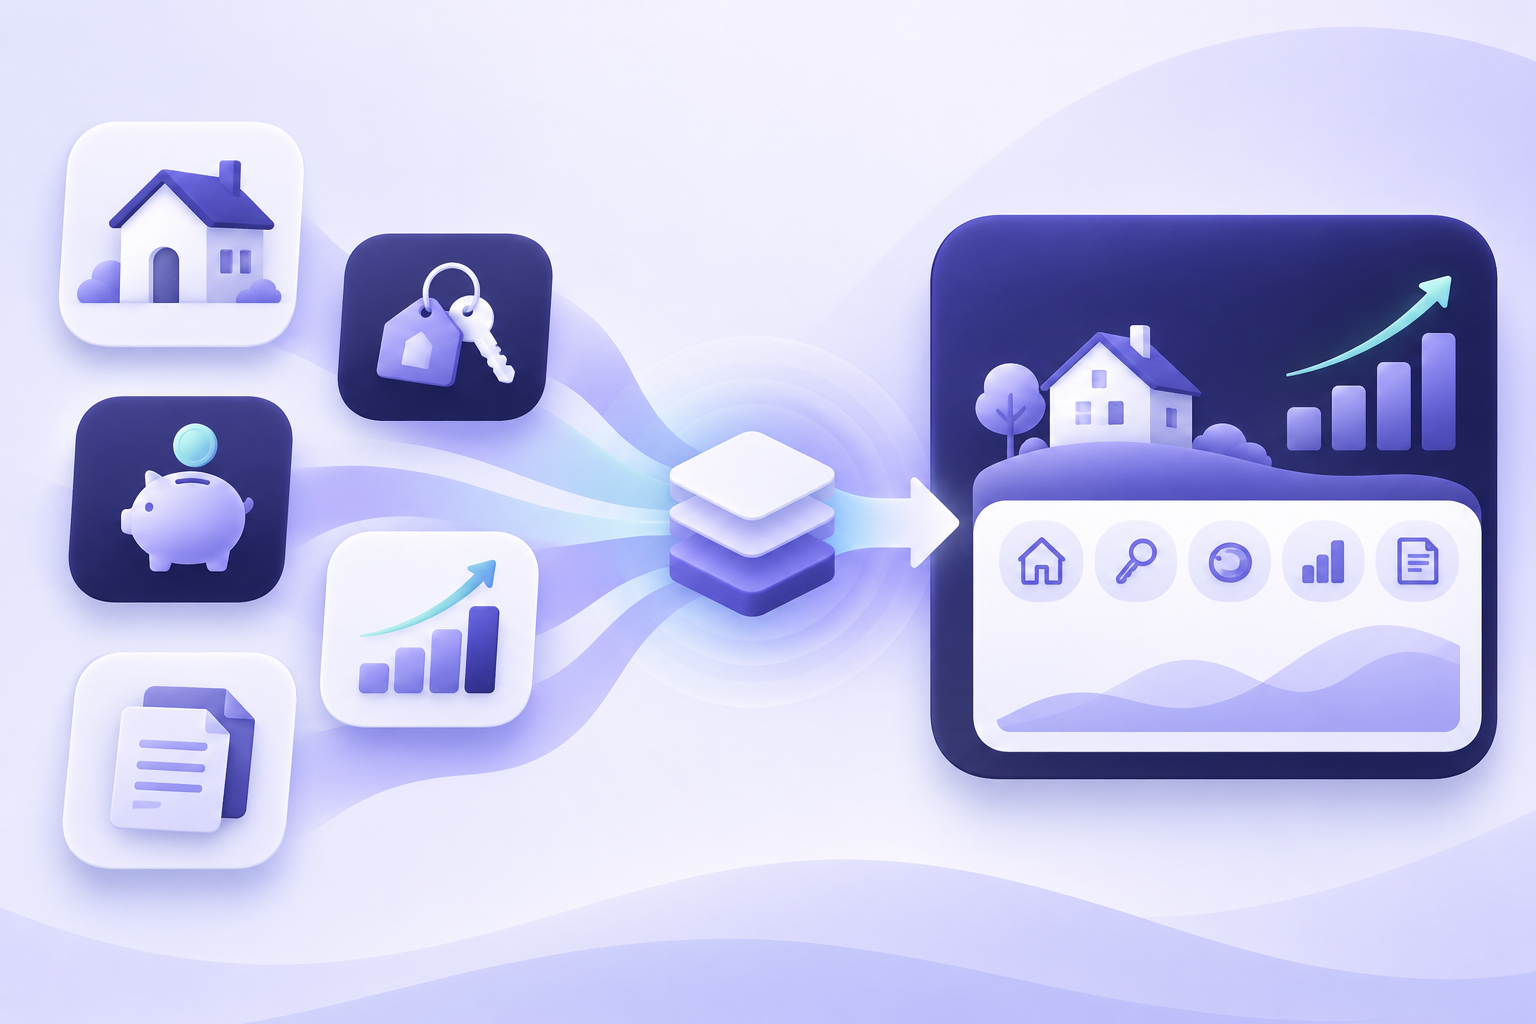
The opportunity isn’t to change how advisers approach financial planning. It is to make it easier to connect one of their clients’ largest assets with the wider advice process.
Property already influences many of the conversations advisers have every day, from retirement planning and inheritance tax to later-life lending, Retirement Interest-Only (RIO) mortgages and estate planning. Understanding a client’s property position becomes increasingly important when exploring the full range of planning options.
Ultimately, this isn’t a product challenge. It is an integration challenge.Helping advisers access property information alongside pensions, savings and investments makes it easier to connect conversations, identify opportunities and deliver the joined-up financial planning that clients increasingly expect.
What does that look like in practice?
It starts with asking broader questions. If a significant proportion of a client’s wealth is tied up in their home, how does that shape the decisions they’re making? For example:
Should downsizing become part of the retirement plan? Would a Retirement Interest-Only (RIO) mortgage be appropriate? Is equity release worth exploring? Does inheritance tax planning change? Should gifting happen sooner?
None of these conversations happen in isolation. Each one influences the next. Looking at wealth as a whole gives advisers more context, helping them explore options, connect different areas of planning and deliver advice that reflects the reality of their clients’ financial lives.
Better conversations need better infrastructure
Of course, none of that works particularly well if the underlying tools are still fragmented. It’s not enough to tell advisers to “think more holistically” if the information they need still sits across disconnected systems.
Property is a good example. Valuations, equity modelling, later-life lending, Retirement Interest-Only (RIO) mortgages and referral journeys often sit outside the core advice process, even though they’re closely connected to wider retirement, tax and estate planning decisions.
Technology isn’t there to replace advisers. It’s there to remove friction. The less time advisers spend gathering information, the more time they can spend understanding clients’ goals, exploring different scenarios and helping people make better decisions.
If the industry wants more joined-up financial planning, the infrastructure needs to support it.
This only works if it scales
Property shouldn’t only become part of financial planning only when someone reaches a later-life lending decision. Those conversations need to start much earlier.
Those are the environments where property can become a natural part of financial planning, rather than a conversation that’s only introduced when a client reaches a later-life lending decision. By bringing property into mainstream advice journeys earlier, advisers can help clients understand more of their options before decisions become urgent.
Because the challenge isn’t simply whether solutions exist. It’s whether people discover them early enough to make informed choices.
What’s next?
The direction of travel is clear. As financial planning becomes increasingly connected, and as more clients require tax and estate planning, the role of property will continue to grow. The opportunity now is making it easier for advisers to bring property into the advice journey alongside pensions, savings and investments.
Ultimately, better financial planning isn’t about giving one asset more attention than another. It’s about helping advisers see the whole picture, so they can have better conversations, explore more options and deliver advice that reflects every part of their clients’ wealth.